Access your Back Office at your fingertips.
Download the app now on Google Play Store.
Scan the QR code
You can also scan QR code with your phone to download the app.
Understanding a user’s loan profile on Lendsqr
Updated
On this page
Introduction
A loan officer opens a borrower’s application. The borrower looks good on the surface, but something feels off. Their salary looks right, their documents are submitted, but their previous loan requests tell a different story. Three declined applications in the last six months, all for the same product.
Without a complete view of the borrower’s loan profile, that pattern stays hidden. With it, your team catches it before making a costly approval decision.
In the Lendsqr admin console, every loan application includes a complete loan profile that gives your team everything they need to thoroughly review a borrower. This guide explains what each section of the loan profile contains and how to use it effectively during the credit review process.
What is a user’s loan profile?
A user’s loan profile is a consolidated view of everything the Lendsqr admin console knows about a borrower in the context of a specific loan application. It brings together personal details, financial data, repayment history, document status, and automated decision checks into one place.
Your credit team does not need to switch between screens or pull information from multiple sources. Everything relevant to the approval decision sits within the loan profile, organized into distinct sections that each serve a specific purpose.
The sections of a user’s loan profile
Summary
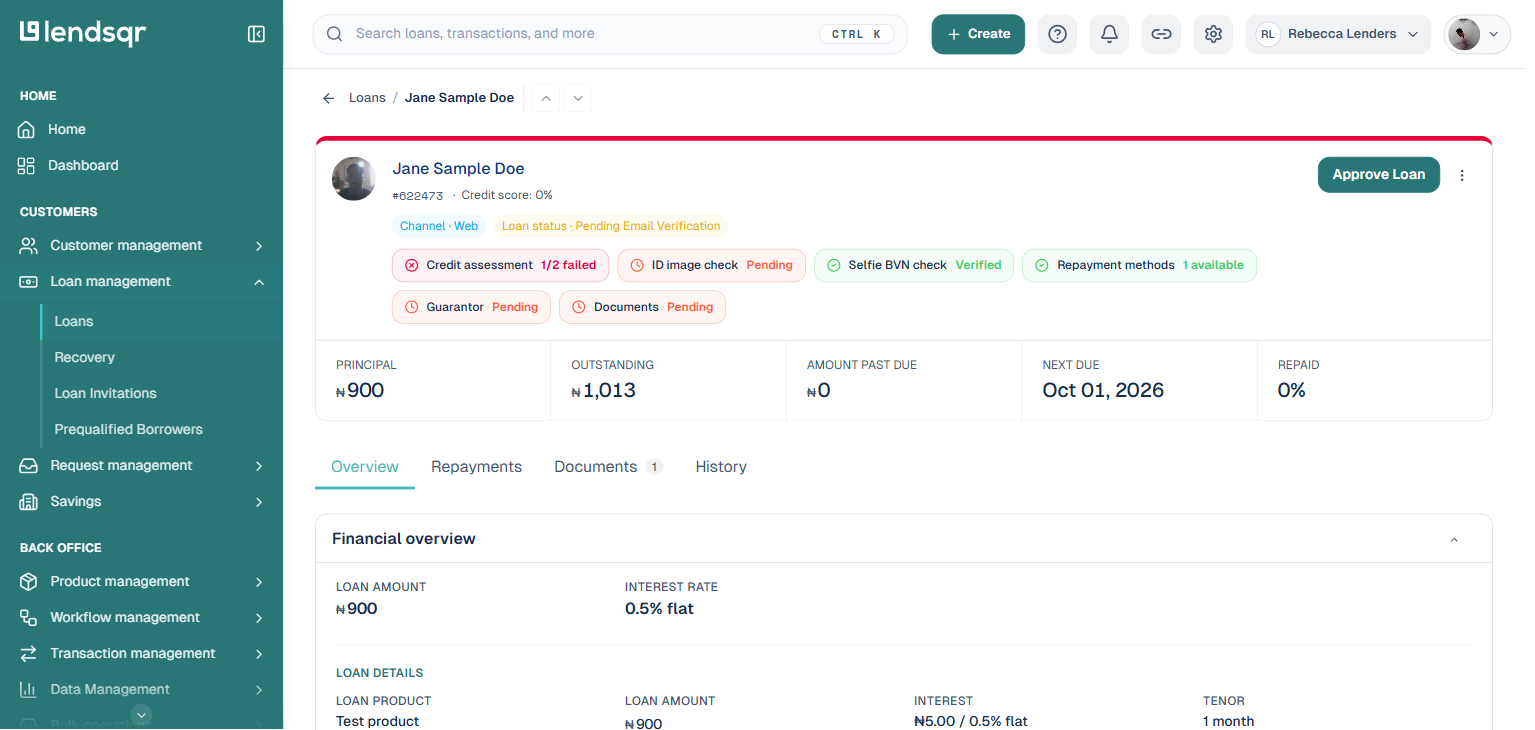
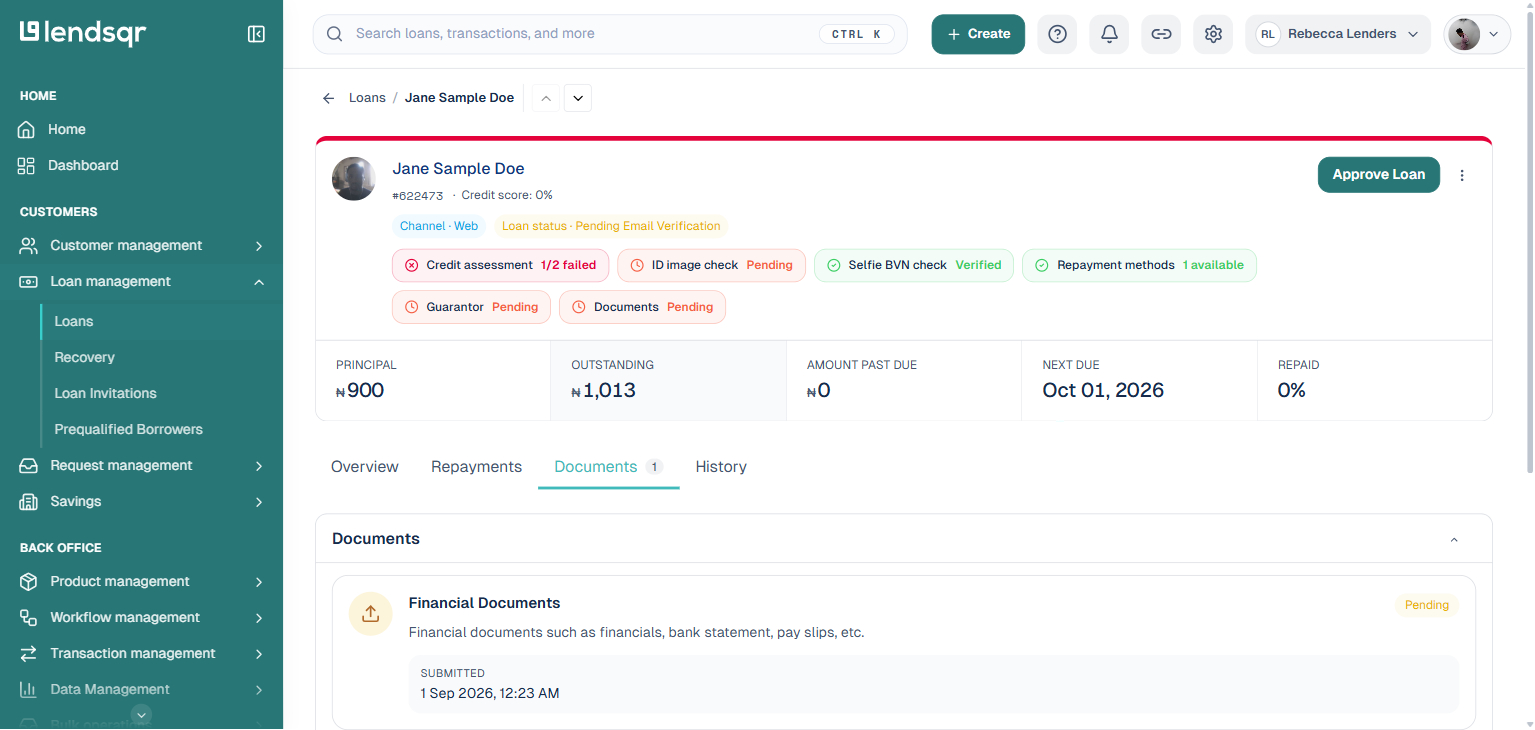
The top of the loan profile is the first thing you see when you open a loan request. It displays the borrower’s name, their credit score, the loan status, and a row of decision-check badges (credit assessment, ID image check, selfie BVN check, repayment methods, guarantor, and documents), plus the principal, outstanding balance, amount past due, next due date, and percentage repaid.
Use this summary to get an immediate read on the borrower before diving deeper. All-green badges and a clean repayment record signal a lower-risk applicant. Failed or pending badges signal the need for closer review.
Loan details, fees, and schedule
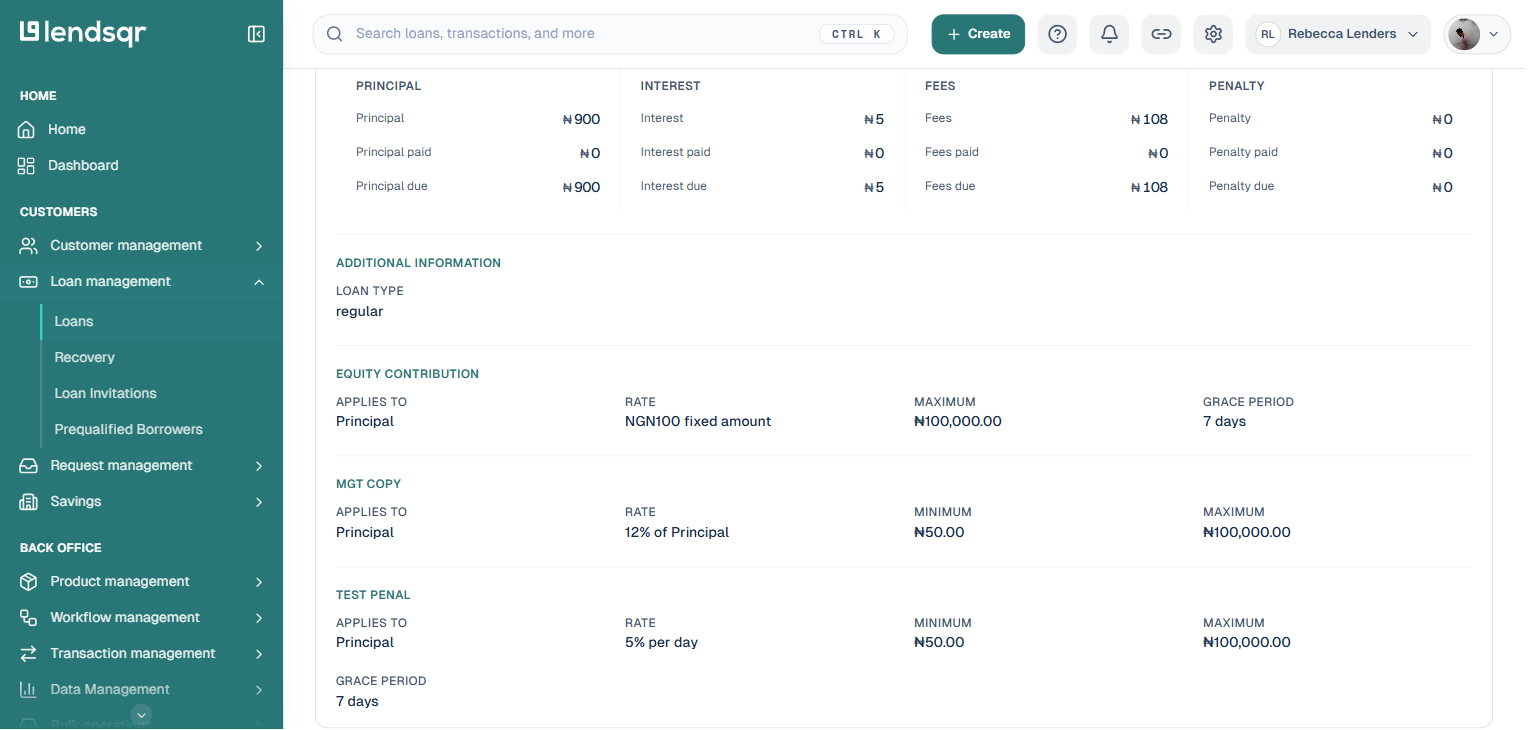
The Financial overview section, on the Overview tab, contains the specifics of the loan the borrower applied for: the loan product, principal, interest, tenor, application and end dates, and purpose. Below it, a repayment breakdown splits the principal, interest, fees, and penalty into paid and due amounts, followed by a full breakdown of any configured fees (management fees, penalties, equity contributions, and so on).
Use this section to confirm that the loan request aligns with the product configuration and that all applicable fees are correctly configured and visible before the loan is approved.
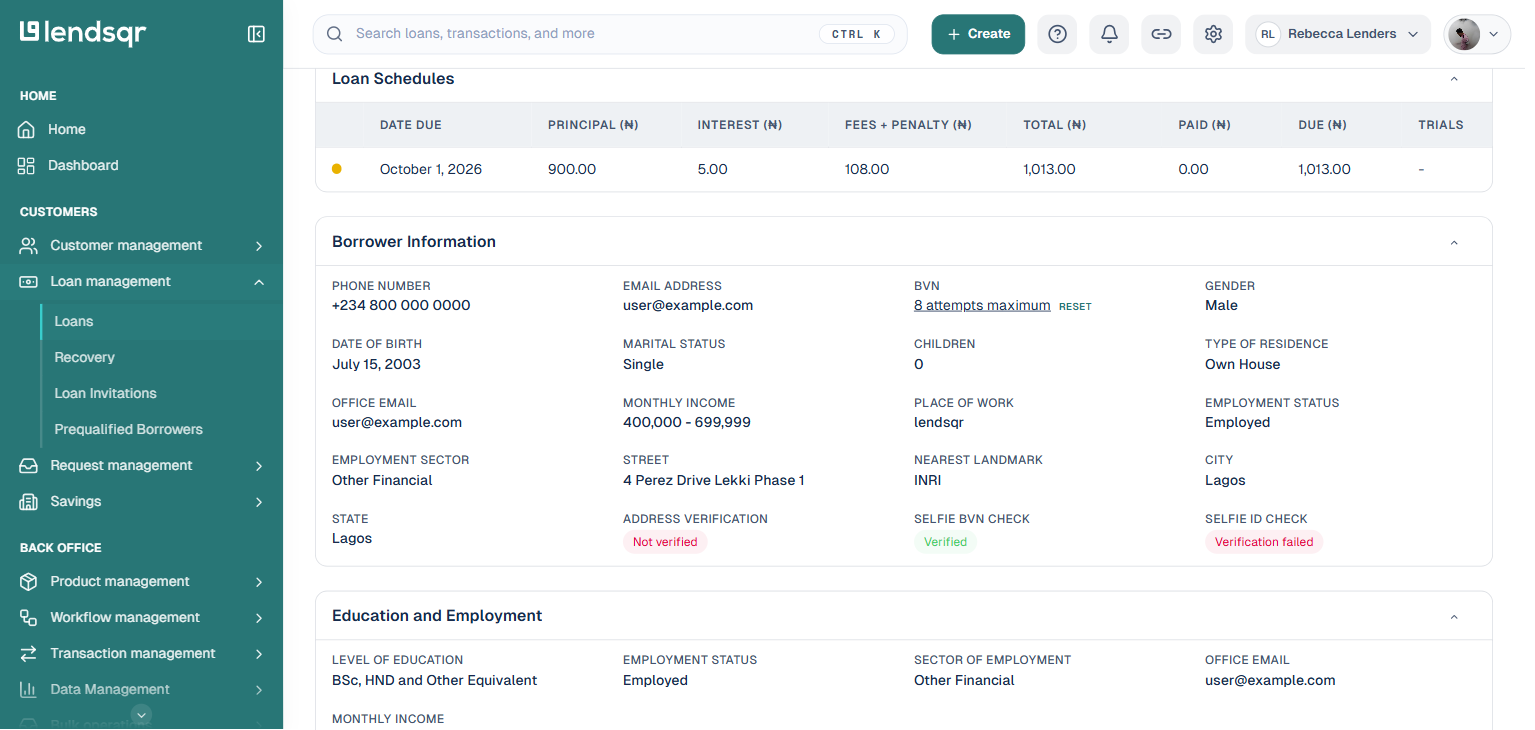
Further down the same Overview tab, the Loan Schedules table shows the full repayment schedule, every due date, the amount due at each stage, and the outstanding balance. Right below it, the Borrower Information section contains the personal details submitted during onboarding: phone number, email, BVN, date of birth, marital status, employment status, and address.
Use the schedule to review the repayment plan before approval, and the borrower information to verify that personal details are complete and consistent with submitted documents. Inconsistencies here are a common fraud signal worth investigating before approval.
Education, employment, cards, and bank accounts
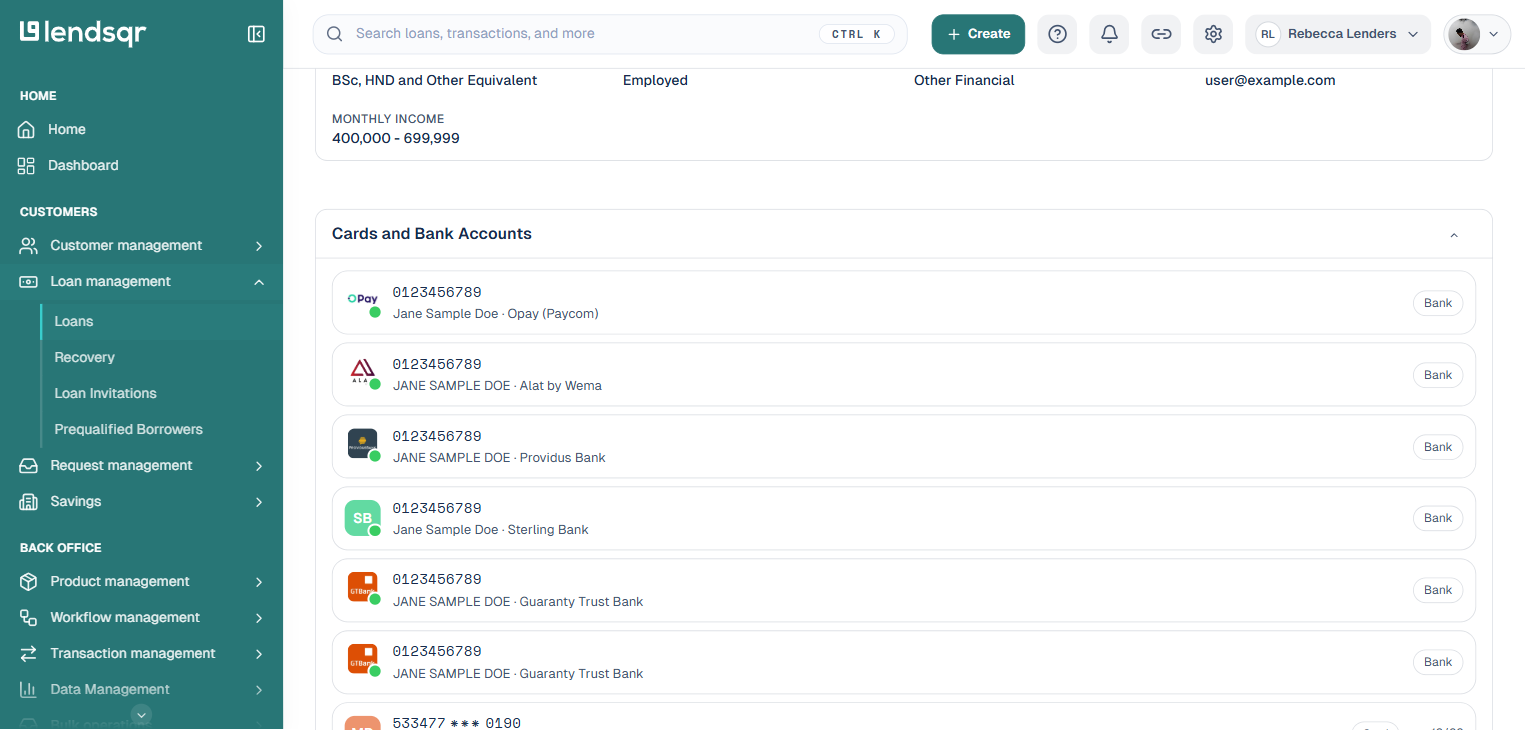
Continuing down the Overview tab, the Education and Employment section displays the borrower’s education level, employment status, sector, and monthly income. Below it, the Cards and Bank Accounts section lists every payment method linked to the borrower’s profile, the channels through which disbursements will be made and repayments collected.
Use education and employment data to assess income stability and repayment capacity. Use the cards and bank accounts section to confirm the borrower has a valid, verified payment method; a missing or unverified account can delay disbursement after approval.
Decision data
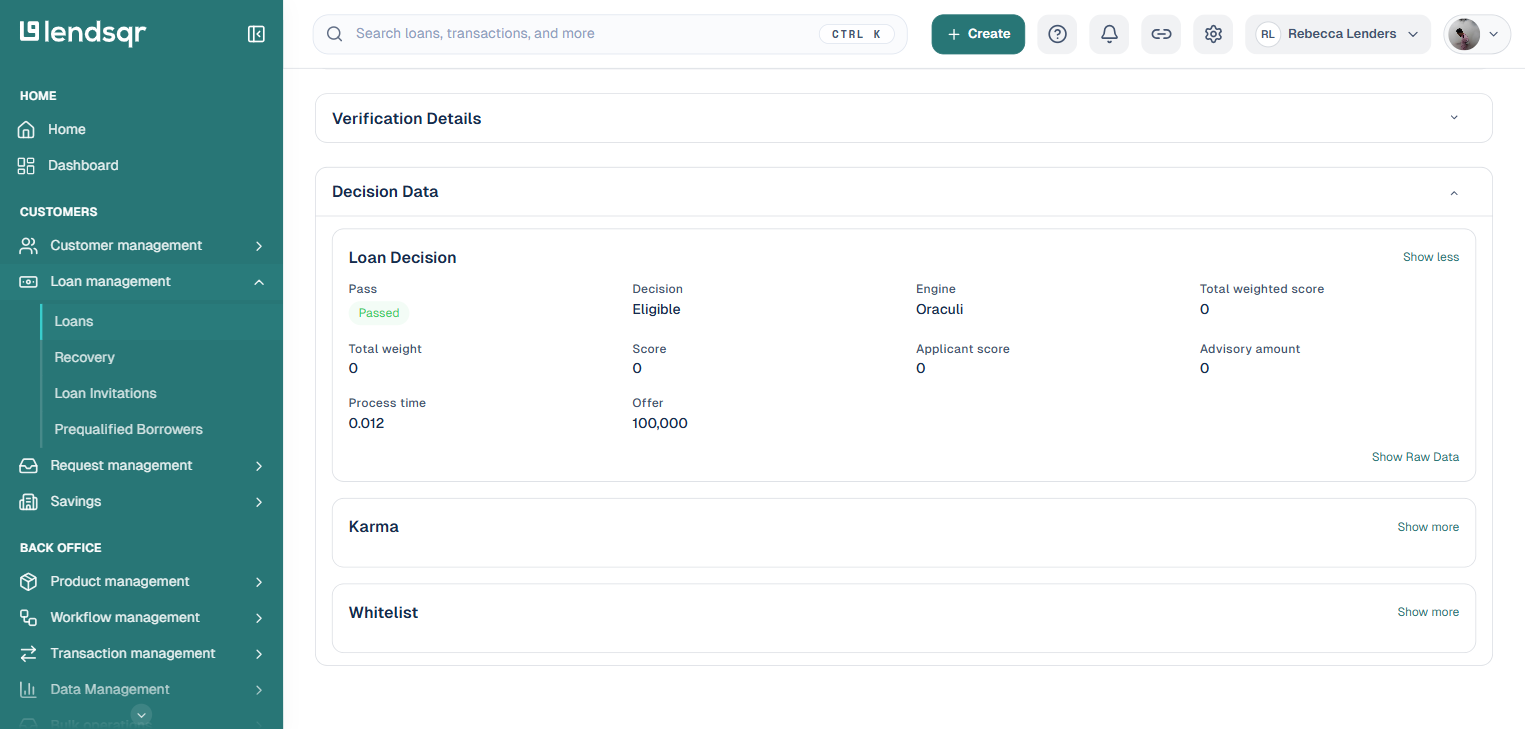
The Decision Data section, at the bottom of the Overview tab, is the most critical part of the loan profile for credit assessment. It shows the output of the automated checks the system ran against the borrower’s application: the Loan Decision card (pass/fail, decision, engine, scores, and offer amount), plus Karma and Whitelist checks configured on your credit risk rule.
Use this section to understand exactly what the system found before making your final approval or decline decision. The decision data gives you the evidence to support a consistent, defensible credit decision.
Documents
The Documents tab, next to Overview, displays all KYC documents the borrower submitted, each with its current status: pending, approved, or rejected.
Use this tab to review submitted documents before making an approval decision. If a required document is missing or rejected, you can identify the gap here and follow up with the borrower before proceeding.
Previous loans and loan requests
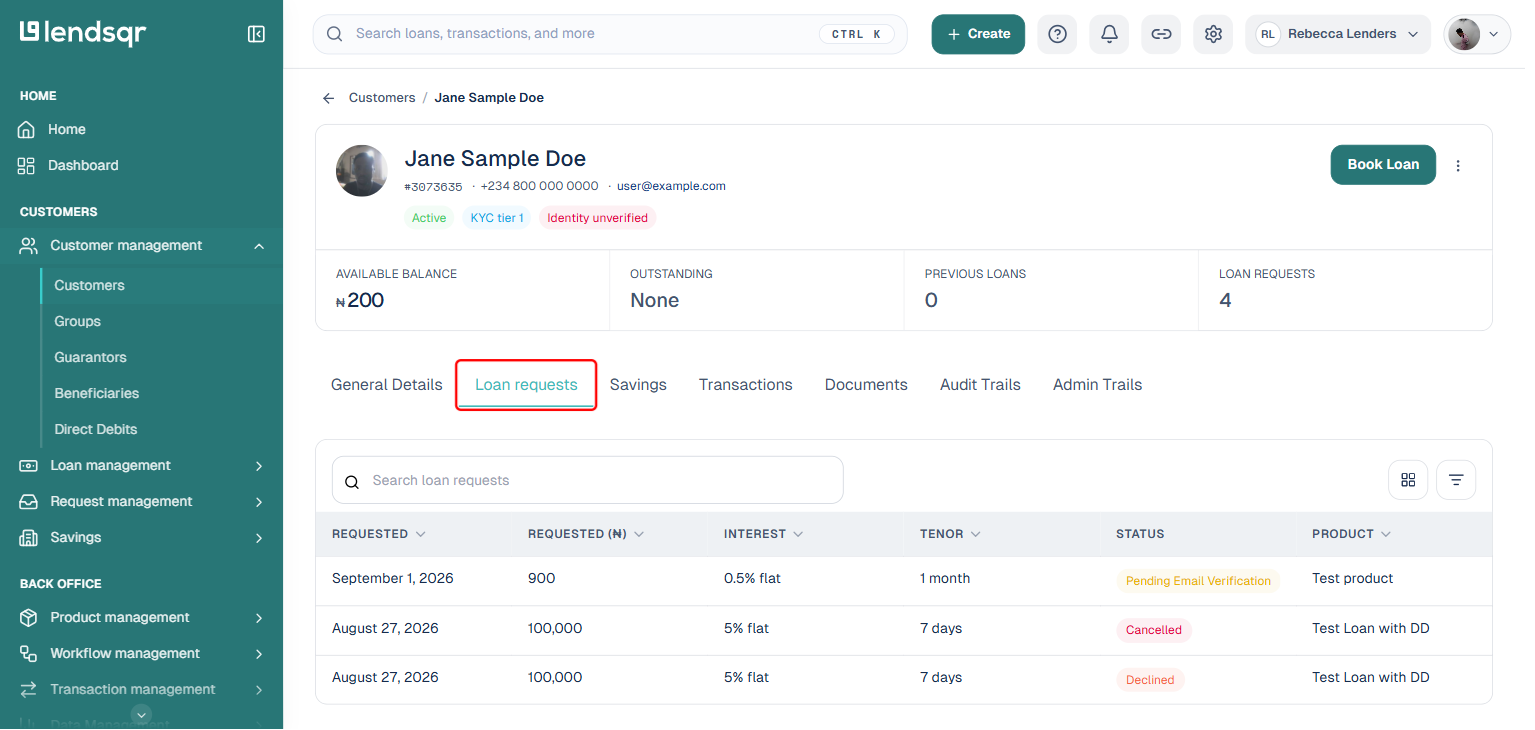
The borrower’s full loan history now lives on their customer profile rather than inside each individual loan’s page. Open the borrower’s customer profile and use the “Previous Loans” and “Loan Requests” counters, or the “Loan requests” tab, to see every loan the borrower has taken or applied for on your platform, including declined or cancelled requests. Click any record to view the reason a request was declined or unsuccessful.
Use this to assess the borrower’s repayment track record and identify patterns, such as multiple recent declined requests for the same product, which may indicate the borrower consistently fails a specific credit check.
How Lendsqr brings it all together
The loan profile on Lendsqr is designed to remove the guesswork from credit decisions. Instead of piecing together information from multiple sources, your team reviews a single profile that surfaces everything relevant to the decision in one structured view.
This is particularly valuable for lenders who process high volumes of applications. When every loan officer follows the same profile structure, credit decisions become more consistent, faster, and easier to audit. A senior credit manager can review any decision and immediately understand what information was available and what the automated checks returned.
Can I approve a loan directly from the loan profile? Yes. The approval and decline options are accessible from the loan profile page. See Approving and declining a loan request on Lendsqr for the full process.
Can I edit the borrower’s personal details from the loan profile? Personal details can be updated from the borrower’s customer profile rather than directly from the loan profile. Navigate to the customer profile to make corrections before returning to the loan review.
What does it mean if the decision data shows a failed check? A failed check means the borrower did not meet the criteria defined in your credit risk rule for that specific module. Depending on how your model is configured, a failed check may automatically decline the application or flag it for manual review. Review the failed check and apply your credit policy to determine the appropriate next step.
Who can view a user’s loan profile? Any team member with the appropriate role and permissions can view loan profiles. The ability to edit schedules or take approval actions may be restricted to specific roles depending on your organization’s configuration.